If you’ve ever thought, “I don’t want to make too much money because it’ll push me into the next tax bracket,” you’re definitely not alone.
It’s one of the most persistent tax myths out there.
Someone gets a raise and worries that the extra income will push their entire salary into a higher tax bracket. A business owner has a particularly profitable year and wonders whether making more money could somehow leave them with less money after taxes.
That’s not how federal income tax brackets work.
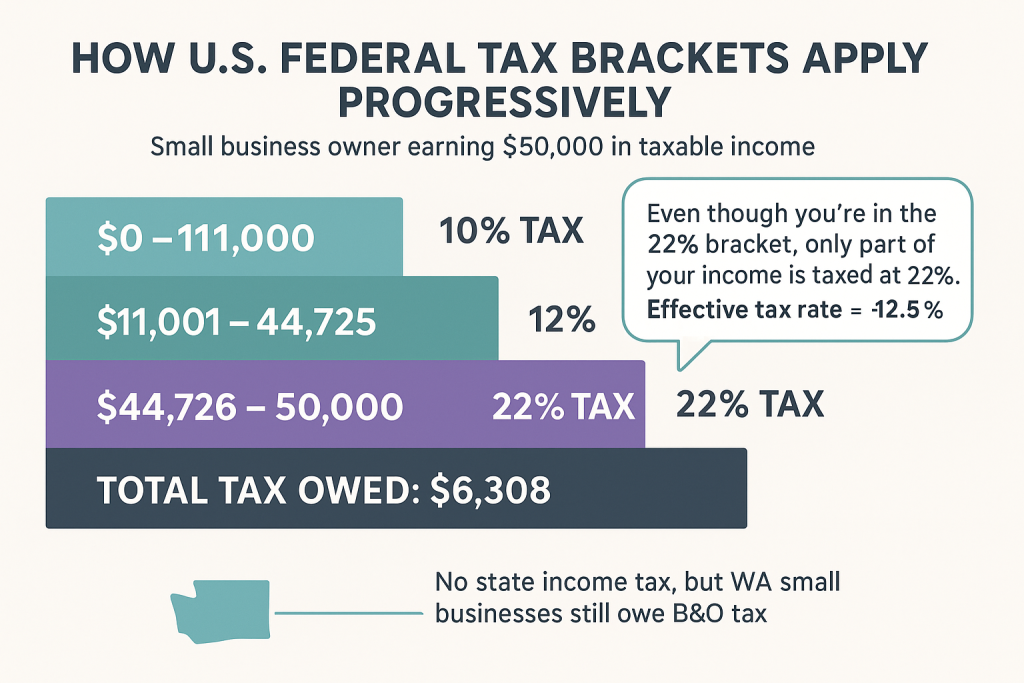
The US federal income tax system uses marginal tax rates, which means different portions of your taxable income are taxed at different rates.
Moving into a higher tax bracket doesn’t mean your entire income suddenly gets taxed at that higher rate.
And for business owners, understanding that distinction can make tax planning much less intimidating.
Tax Brackets Are Marginal, Not Flat
Here’s the most important thing to understand:
When you move into a higher tax bracket, only the income that falls within that bracket is taxed at the higher rate.
The income below that threshold continues to be taxed at the lower rates.
For 2026, the federal income tax rates for individual taxpayers range from 10% to 37%. For a single filer, for example, the 22% bracket begins at $50,400 of taxable income, while the 24% bracket begins at $105,700.
That does not mean someone earning $105,701 suddenly pays 24% on their entire taxable income.
Only the dollar above the applicable threshold enters the 24% bracket.
Here’s a simplified example
Imagine a single taxpayer has $60,000 of taxable income in 2026.
Part of that income is taxed at 10%.
The next portion is taxed at 12%.
The portion that falls above the applicable 22% threshold is taxed at 22%.
The taxpayer is therefore considered to be in the 22% marginal tax bracket.
But they aren’t paying 22% on all $60,000.
Their overall tax rate—their effective tax rate—is lower because some of their income was taxed at the lower rates.
That’s the distinction that gets lost when people talk about “being in the 22% bracket.”
Your marginal tax rate tells you the rate that generally applies to your next dollar of taxable income.
Your effective tax rate tells you what percentage of your overall taxable income you’re actually paying in federal income tax.
They’re not the same thing.
So Can Making More Money Ever Leave You With Less Money?
Not because of the ordinary progressive federal income tax brackets themselves.
If an additional $1 of taxable income moves you into a higher bracket, that doesn’t cause the rest of your income to be retroactively taxed at the higher rate.
You’ll still generally have more money after taxes because you earned more money before taxes.
That’s why the idea that you should turn down a raise, avoid a profitable project, or stop taking on business because it’ll “put you into the next bracket” doesn’t make sense by itself.
If you’re deciding whether to earn another $10,000, the question isn’t:
“Will I be in a higher bracket?”
It’s:
“How much of that additional $10,000 will I keep after the applicable taxes and other effects?”
That’s a much more useful question.
Your Tax Bracket Is Based on Taxable Income
There’s another important distinction here.
People often say things like:
“I make $100,000, so I’m in the 24% tax bracket.”
Not necessarily.
Tax brackets apply to taxable income, not simply your gross salary or business revenue.
Before you get to taxable income, there may be adjustments, deductions, and other tax calculations that affect the number.
For example, a business owner might generate $150,000 of business income but have deductible business expenses that reduce the amount of income ultimately subject to federal income tax.
A taxpayer may also claim the standard deduction or itemize deductions, depending on which is appropriate.
For 2026, the standard deduction is $16,100 for single filers, $24,150 for heads of household, and $32,200 for married couples filing jointly.
So don’t determine your tax bracket simply by looking at your gross income.
Your Tax Bracket Isn’t Your Overall Tax Rate
This distinction is particularly important when you’re making business decisions.
Suppose you’re a business owner in the 24% marginal bracket.
You might hear someone say:
“That expense saves you 24% in taxes.”
That’s not necessarily the right way to think about it.
A deduction reduces taxable income. The actual tax savings depend on where the deduction falls within your tax situation and can be affected by other rules.
If you spend $10,000 on something your business genuinely needs, a deduction isn’t giving you $10,000 back.
At a hypothetical 24% marginal rate, a $10,000 deduction might reduce federal income tax by roughly $2,400, subject to the applicable rules.
You’re still out $7,600.
That’s why “buy something because it’s deductible” is terrible tax planning.
A tax deduction can make a smart business purchase more tax-efficient.
It doesn’t turn an unnecessary purchase into a profitable one.
Why Tax Brackets Matter So Much for Business Owners
Tax brackets become particularly interesting for entrepreneurs because business income can fluctuate dramatically from year to year.
You might make $80,000 one year.
Then $140,000.
Then $220,000.
Then you have a bad year and make $60,000.
That volatility creates opportunities for tax planning.
The goal isn’t necessarily to stay in the lowest possible bracket.
Instead, you’re trying to understand when income will be recognized, when deductions will be available, and how those decisions interact with your overall tax situation.
That can lead to several useful strategies.
1. Think About When Income and Expenses Hit
If you have some control over the timing of income and deductible expenses, timing can matter.
For example, imagine you’re having an unusually profitable year and expect next year to be substantially slower.
Depending on your accounting method and the specific circumstances, you may want to look at whether certain legitimate business expenses can be incurred in the current year or whether certain income can appropriately be recognized later.
Conversely, if you expect next year to be significantly more profitable, accelerating certain deductions into the current year could potentially be more valuable.
This isn’t a license to manipulate your books or arbitrarily move income between tax years.
Taxpayers generally have to follow the accounting method and tax rules that apply to their business.
But understanding the timing of income and deductions is an important part of tax planning.
2. Don’t Buy Equipment Just for the Deduction
Business owners frequently hear about Section 179 and bonus depreciation and immediately start looking at new equipment.
There can be legitimate tax advantages to purchasing qualifying business property.
But the tax deduction should be the secondary consideration, not the reason for buying something you don’t need.
Ask:
“Would I buy this equipment if there were no tax deduction?”
If the answer is yes, then the tax treatment becomes an important part of the purchasing decision.
If the answer is no, you’re probably spending a dollar to save a fraction of that dollar in taxes.
That’s not a tax strategy.
That’s just shopping.
3. Retirement Contributions Can Change the Equation
Retirement planning can also affect your taxable income.
Depending on your business structure and eligibility, a business owner might have options including a SEP IRA, SIMPLE IRA, 401(k), or other retirement arrangement.
The contribution rules and limits vary by plan.
For example, the 2026 employee elective-deferral limit for most 401(k) plans is $24,500, while the contribution limit for a SEP IRA is generally the lesser of 25% of compensation or $72,000 for 2026. SIMPLE IRA salary-reduction contributions are generally limited to $17,000.
The right retirement plan depends heavily on your business structure, income, employees, and goals.
But the larger point is that retirement planning and tax planning can overlap.
You’re potentially reducing current taxable income while putting money toward your future rather than simply spending money to create a deduction.
4. Don’t Forget About HSAs
If you’re eligible to contribute to a Health Savings Account, an HSA can also have significant tax advantages.
For 2026, the HSA contribution limit is $4,400 for self-only coverage and $8,750 for family coverage, assuming you meet the eligibility requirements.
HSA contributions can generally be deductible, or can be made through an employer’s cafeteria plan on a pre-tax basis, depending on the circumstances.
And unlike buying something your business doesn’t need just to generate a deduction, you’re potentially putting money into an account that can be used for qualified medical expenses.
Again, eligibility matters.
5. Look at Your Business Structure
Your business structure can affect your overall tax situation, although it’s important not to confuse entity structure with your personal income tax bracket.
A sole proprietorship, partnership, S corporation, and C corporation can have very different tax consequences.
For example, an S corporation owner may have wages subject to payroll taxes as well as pass-through business income reported on the owner’s individual return.
A sole proprietor generally reports business income on Schedule C and may also owe self-employment tax.
An LLC, meanwhile, doesn’t tell you the entire tax story because an LLC can have different federal tax classifications.
That’s why “What tax bracket am I in?” is only one piece of a business owner’s tax-planning puzzle.
You also need to consider what type of income you’re earning and which taxes apply to it.
6. Don’t Confuse Income Tax With Every Other Tax
Your federal income tax bracket isn’t necessarily the rate that applies to every tax you owe.
Business owners may encounter several different taxes, including:
- Federal income tax
- Self-employment tax
- Payroll taxes
- State and local taxes
- Capital gains taxes
- Net Investment Income Tax, when applicable
- Excise taxes and other industry-specific taxes
Washington business owners, for example, may also have state B&O tax obligations even though Washington doesn’t have a traditional individual income tax on wages.
And Washington’s B&O tax generally applies to gross receipts rather than profit.
So a business owner shouldn’t look at a federal marginal tax bracket and assume that it represents their total tax rate.
It doesn’t.
What About Capital Gains?
Another wrinkle: not all income is necessarily taxed using the ordinary income tax brackets.
Certain long-term capital gains can qualify for preferential federal tax rates.
That means the tax rate that applies to a dollar of long-term investment gain can be different from the marginal rate that applies to a dollar of ordinary income.
This is another reason the phrase “I’m in the 32% tax bracket” doesn’t mean every dollar you earn is taxed at 32%.
Different types of income can be subject to different rules.
What Does “Bracket Management” Actually Mean?
For a business owner, tax planning isn’t about desperately trying to avoid crossing some magical income line.
It’s about understanding where additional income will be taxed and whether you have legitimate opportunities to change the timing or character of income and deductions.
Imagine you expect your business to have an unusually profitable year.
Instead of waiting until tax filing season to discover what happened, you could have your CPA project your taxable income during the year.
That projection can help you evaluate whether it makes sense to:
Increase retirement contributions?
Make a planned equipment purchase?
Review your business structure?
Adjust estimated tax payments?
Look at charitable giving?
Evaluate whether income or expenses can legitimately be timed differently?
Or simply accept the higher tax bill because the business had a fantastic year?
Sometimes paying more tax is the correct answer.
If your business makes an additional $100,000 of profit, paying more tax on that $100,000 isn’t a failure.
It means you made more money.
The Goal Isn’t to Pay the Least Tax Possible
This may sound strange coming from a CPA firm, but it’s worth saying:
The goal isn’t necessarily to pay the lowest possible tax bill.
The goal is to pay the amount of tax you’re legally required to pay while making financial decisions that actually make sense for you and your business.
If you spend $100,000 unnecessarily to save $24,000 in taxes, you’ve made yourself poorer.
If you invest $100,000 in equipment that your business genuinely needs, and that purchase also produces a legitimate tax benefit, that’s a different story.
Good tax planning sits at the intersection of tax savings and good financial decisions.
A Higher Tax Bracket Isn’t a Bad Thing
Getting into a higher tax bracket usually means something pretty simple:
You made more taxable income.
That’s generally a good problem to have.
Don’t turn down profitable work because you’re afraid of “losing money” to taxes.
Don’t avoid a raise because you think your entire salary will suddenly be taxed at a higher rate.
And don’t spend money you don’t need simply because someone told you it’s “a write-off.”
Instead, understand your marginal tax rate, your effective tax rate, the types of income you’re earning, and the deductions and credits that actually apply to your situation.
For business owners, that information can make tax planning much more useful than simply trying to avoid a particular bracket.
The Bottom Line
Tax brackets are designed to be progressive.
Moving into a higher bracket doesn’t mean your entire income gets taxed at that higher rate. It means the next portion of taxable income is generally taxed at the higher marginal rate.
For 2026, federal ordinary income tax rates range from 10% to 37%, with the thresholds adjusted for inflation.
For entrepreneurs, the bigger opportunity isn’t obsessing over the bracket you’re in.
It’s understanding how your business income, deductions, retirement contributions, entity structure, and timing decisions affect your overall tax picture.
And remember the golden rule of tax planning:
Never spend a dollar just to save a quarter in taxes.
If the business needs the equipment, make the purchase.
If you need the retirement savings, make the contribution.
If your business had an incredible year, enjoy the fact that it had an incredible year—even if that means paying more taxes.
The goal of good tax planning isn’t to make your tax bill disappear.
It’s to make sure you’re not paying more than you legally have to while keeping your money working toward the things you actually want.